October 28, 2025
October 1, 2026
Author: João Lages
Asset tokenization is the use of a programmable digital record to represent and administer a legally defined claim on an asset. The token may record a share, note, fund unit, beneficial interest or contractual entitlement. It does not, by itself, transfer land, perfect security, establish custody or guarantee that a buyer will exist.
That distinction is the difference between a credible investment product and a digital wrapper. The Bank for International Settlements describes tokenization as recording claims on real or financial assets on a programmable platform. Its 2025 analysis of the next-generation financial system emphasises the integration of messaging, reconciliation and asset transfer. For an issuer, those efficiencies only become useful when the off-chain claim, the controlling ownership record and the operating process agree.
This guide explains what asset tokenization changes in practice, which structures produce different investor rights, and how to decide whether a token is justified. The intended reader is an asset owner, product team or investment professional evaluating a real transaction—not someone choosing a blockchain before deciding what investors will own.
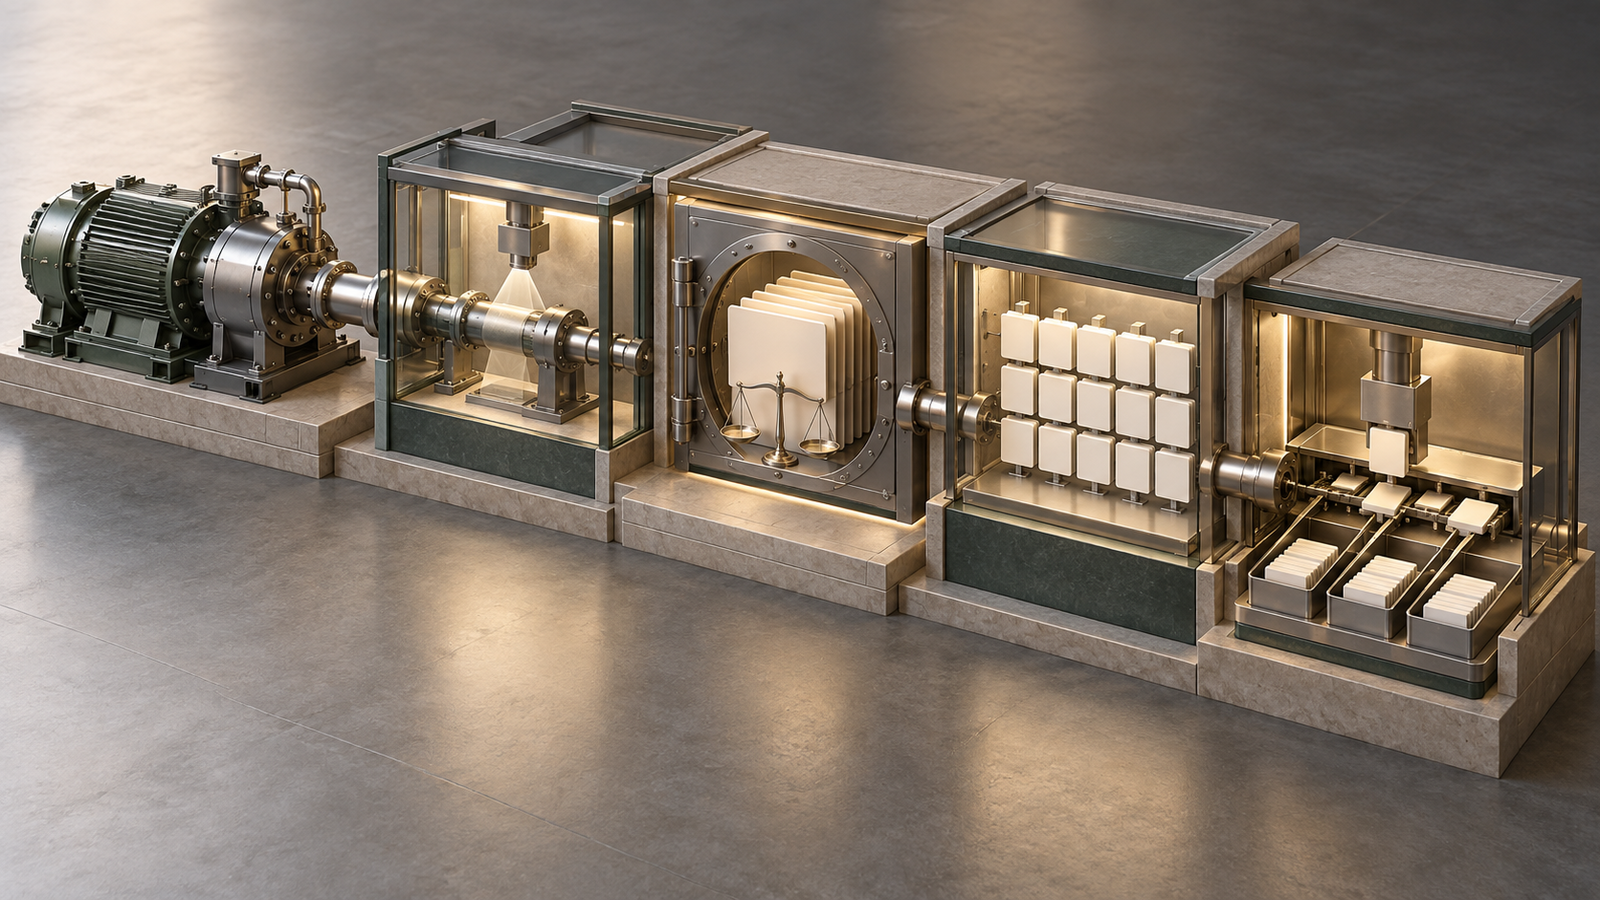
A tokenization project should be designed in four connected layers. A defect in any one can make the remaining three ineffective.
The first layer is the source of value: a property, operating company, loan, machine, commodity, artwork, licence or portfolio. The asset must be identifiable and capable of producing a defined economic outcome, such as rent, interest, dividends, sale proceeds or physical redemption. Due diligence still covers title, liens, valuation, insurance, condition, counterparties and the risks that interrupt cash flow. Tokenization does not improve a weak lease, an unperfected receivable or an overvalued collectible.
The second layer determines what the investor owns and who owes the obligation. The token may represent a direct share in the asset-owning company, a note issued by a special-purpose vehicle (SPV), a fund interest or a contractual claim linked to an asset. These are not interchangeable. They create different priorities, governance rights, insolvency exposures and regulatory classifications.
A promise that each token is “backed by property” is incomplete. Investors need to know whether the issuer owns the property, whether a senior lender has first-ranking security, whether token holders have security through a trustee, and whether their claim survives the platform operator's failure. The legal documents create these rights; the code should implement them faithfully.
The third layer answers which record proves the investor's entitlement. In some structures, a distributed ledger can be the legally effective register. In others, it is an operational record reconciled to a statutory shareholder register, registrar, custodian or central securities depository. The hierarchy must be explicit when records diverge.
This decision also governs lost keys, inheritance, court orders, sanctions freezes and erroneous transfers. A professional product needs an authorised recovery and correction process. Treating private-key possession as irreversible legal ownership may conflict with the instrument terms and with duties imposed on the issuer or registrar.
The fourth layer keeps the product functioning after issuance. It includes investor onboarding, payment, minting, transfers, distributions, voting, reporting, redemption, defaults and final cancellation. A smart contract can enforce objective rules—for example, rejecting a transfer to an ineligible wallet or calculating a coupon from verified inputs. It cannot replace judgement about a disputed valuation, covenant waiver or enforcement strategy.
The four layers should be tested as one system. The token supply must reconcile to the legal instrument. Investor eligibility must match the permitted distribution route. Cash must move through accounts controlled by the documented waterfall. Administrative powers to mint, freeze, force-transfer or burn must belong to named parties acting under defined authority.
The right structure depends on the commercial objective. The following comparison is more useful than asking whether an asset can technically be tokenized.
A company issues shares whose ownership is represented digitally. Investors receive company-law rights such as voting, dividends and a residual claim, subject to the share class and constitutional documents. This can work where local law permits the chosen register and the company can operate transfers, corporate actions and recovery coherently. It creates a direct relationship with shareholders but can add cap-table and governance complexity.
An SPV owns the asset or a contractual right and issues shares or notes. This is common when the underlying title cannot conveniently be fragmented or the sponsor wants one entity on the asset register. Investors own an instrument issued by the SPV, not an individual slice of the asset. The SPV's bankruptcy remoteness, fees, secured obligations, accounts and decision rights become central.
A managed vehicle pools capital and invests according to a strategy. Investors hold units or shares in the vehicle rather than fixed interests in each portfolio asset. Tokenization may streamline subscriptions, transfers and recordkeeping, but the manager's discretion, valuation policy, depositary or custody arrangements, liquidity management and fund regulation remain decisive.
An issuer promises payment, delivery or redemption by reference to an asset or price. The holder may have no proprietary interest in the reserve. This structure can support commodity or revenue-linked products, but investors need precise reserve, custody, valuation and redemption terms. If the issuer fails, the difference between segregated assets, perfected security and an unsecured promise becomes critical.
Lympid's guide to security-token structures and infrastructure examines how shares, notes, fund interests and asset-linked securities behave when the digital record is part of a regulated instrument.
Issuance is only the first controlled state change. A credible operating model defines the complete lifecycle:
This sequence reveals whether tokenization reduces a real operational burden. Where ownership changes frequently, distributions involve many holders and eligibility controls must travel with the instrument, a programmable register can reduce reconciliation. For one investor holding one asset to maturity, a conventional database and contract may be simpler.
Assume an SPV owns a leased commercial building and issues tokenized notes. The land register names the SPV, not individual token holders. Tenant rent enters a controlled account. The payment waterfall covers property taxes, insurance and operating costs, then senior mortgage debt, a liquidity reserve and finally interest and principal on the tokenized notes.
The token can maintain the noteholder register, restrict transfers and allocate distributions. It cannot remove the senior mortgage, prevent vacancies or establish the noteholders' priority without effective legal documentation. Before issuance, the product team must decide whether the notes are secured, who holds that security, how the property manager can be replaced and what occurs when rent is insufficient.
Two exit paths also need separate treatment. A secondary transfer changes the holder of the note if an eligible buyer exists. A property sale converts the underlying asset into cash and triggers the waterfall defined in the note terms. Neither event is guaranteed by making the token technically transferable. For a broader asset-class comparison, see Lympid's analysis of the legal claim behind crypto real-world assets.
Consider an SPV that raises capital through tokenized fixed-rate notes and lends the proceeds to a manufacturer buying production equipment. The borrower owns or leases the equipment under the financing documents. Investors hold notes issued by the SPV. Their return depends on the borrower's cash generation, repayment discipline, insurance, the equipment's resale value and effective security.
Monthly borrower payments enter a collection account; investors receive quarterly distributions. The servicing system must reconcile loan principal, bank receipts, reserves and outstanding tokens. If a covenant is breached, the documents should say who can grant a waiver, accelerate the loan, replace the servicer or enforce security. Those are governance decisions, not automatic consequences of a data feed.
This case produces a clear implementation decision. Tokenization may be justified when the issuer expects many investors, recurring distributions and controlled transfers. If one lender funds the facility and holds it to maturity, the same token layer could add cost without changing ownership, servicing or liquidity.
EU regulation is technology-neutral. A token that confers rights equivalent to shares, bonds or other transferable securities may be a financial instrument under MiFID II. ESMA's guidelines on classifying crypto-assets as financial instruments apply a substance-over-form analysis. A novel token name or technical standard does not change the economic rights.
This boundary matters because MiCA excludes crypto-assets that qualify as financial instruments. A tokenized security does not move from securities law into MiCA merely because it uses a blockchain. Depending on the structure, an issuer may also need to assess prospectus rules, fund classification, regulated placement or advice, custody, market infrastructure, anti-money-laundering obligations and national company or property law.
Binding law, supervisory guidance and market practice should not be blended. EU and national law determine the obligations. ESMA guidance supports consistent classification. Practices such as using an SPV, whitelisting wallets or appointing a registrar help implement a structure but do not decide its legal category. Issuers should obtain transaction- and jurisdiction-specific legal, tax and regulatory advice.
Tokenization can make denominations smaller and transfers more programmable. Liquidity still requires eligible buyers, current information, credible valuation, a permitted execution route, custody and a cash-settlement method. A token that moves between wallets may remain difficult to sell. Admission to a venue does not guarantee trading volume, and issuer-facilitated matching is not the same as contractual redemption.
An investment committee should separate four questions: can the smart contract transfer the token; can the proposed buyer legally receive it; can an authorised process execute and settle the trade; and is there enough two-way demand to produce an acceptable price? Any public claim about liquidity should identify the actual exit route, expected holding period, fees, notice periods and the possibility that no buyer is available.
Before choosing technology, the project team should be able to answer seven questions with documentary evidence:
If these answers are weak, tokenization digitises ambiguity. If they are precise, it can connect issuance, eligibility-controlled transfers, investor records, servicing and settlement in a more coherent operating system. Asset owners evaluating an implementation partner can compare Lympid's physical-asset tokenization infrastructure with other approaches by assigning every legal, regulated and operational responsibility—not by treating one platform as a substitute for counsel, custodians, distributors or asset specialists.
The decisive test is therefore simple: use asset tokenization when the programmable record removes a measurable ownership, distribution, servicing or settlement friction. Do not use it as proof of title, asset quality, liquidity or regulatory approval. Those conclusions must come from the claim and the evidence behind it.
Book a call with us today and get a free assessment.