November 19, 2025
October 23, 2026
Author: João Lages
European corn is traded through contracts that specify quality, location, timing and remedies. A token that omits those terms does not create a simpler commodity. It creates a different and often weaker claim. The practical route to tokenizing corn is to begin with a deliverable contract and design the token around its settlement mechanics.
This matters because a tonne in one silo is not automatically equivalent to a tonne in another. Moisture, broken grain, impurities, GMO status, intended use and delivery point affect price and acceptability. Corn also deteriorates in storage, creating losses that cannot be solved by a static on-chain quantity.
Euronext’s corn futures contract shows how a market creates fungibility. The current Euronext corn specification, last updated 13 April 2026, uses 50-tonne trading units, identifies EU origin, sets quality parameters for moisture, broken grains and impurities, and names approved delivery silos. The quoted price only has meaning within that framework.
A token issuer should apply the same discipline. The asset schedule should identify the reference grade, permitted tolerances, crop year, approved locations and treatment of off-specification corn. If the programme uses a benchmark only for valuation, it should disclose basis risk between the benchmark and actual stock.
Suppose a trader holds merchantable corn in an approved Bordeaux-area silo and issues tokens redeemable in 50-tonne blocks. The operational design can align quantity and location with the futures market, but the token is not an Euronext contract. It has its own counterparty, custody and legal terms. A holder must still know who owns the corn, whether the warehouse acknowledges the holder or security trustee, and which costs apply at load-out.
If the same programme allows one-tonne redemptions, it creates a logistics promise that the futures specification does not provide. The operator must decide whether small holders receive cash, aggregate requests or pay additional handling costs.
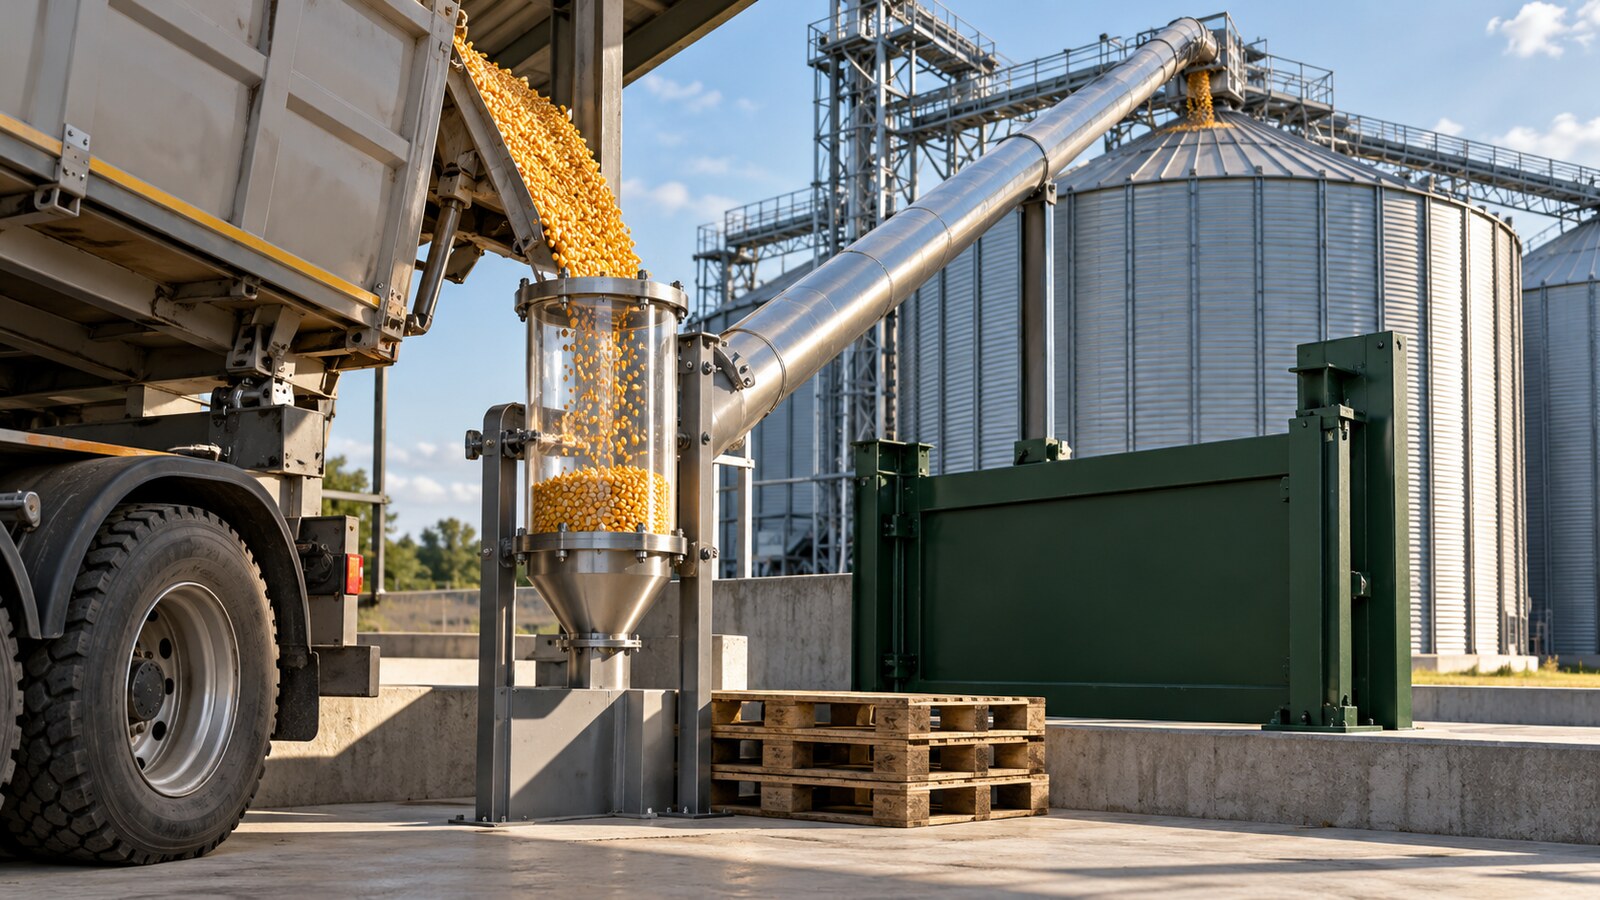
Corn moves through intake, drying, cleaning, storage, sale and dispatch. Weight and quality can change at each stage. The token programme should distinguish:
Only eligible, controlled inventory should support freely transferable tokens. Pre-delivery crop finance can be tokenized, but it is a different credit exposure. It relies on the grower’s performance, crop yield and contract enforceability rather than warehouse control.
An inventory token can give a claim on corn already in an identified silo. Coverage can be reconciled against warehouse records. A forward-finance token funds future delivery and therefore needs underwriting, covenants, monitoring and remedies for crop failure or non-delivery. Presenting both as “corn-backed” conceals the main risk distinction.
Quality disputes often turn on how and when the sample was taken, retained and tested. The documents should identify the sampler, method, laboratory, tolerance, retest process and binding result. An oracle that writes a laboratory value to a ledger is useful only if the sampling chain is defensible.
For food uses, contaminant limits also matter. The European Commission confirms that maximum levels for certain food contaminants are set by Regulation (EU) 2023/915, while official mycotoxin sampling and analysis are governed by Implementing Regulation (EU) 2023/2782. See the Commission’s contaminants legislation overview.
A token programme should have a quarantine process for a failed or pending test. The corresponding inventory must be removed from the borrowing base, and transfers or redemptions may need to pause. The operator should avoid socialising one bad lot across good inventory unless the pool rules explicitly permit it and the economics are disclosed.
Commercial silos commonly commingle grain of compatible grade. In that setting, promising ownership of the “same corn” is unrealistic. A better design may grant a proportional entitlement to an identified bulk pool, supported by warehouse acknowledgement and rules on substitution, shrinkage and shortfall.
The warehouse contract should prohibit unauthorised release, define lien priority and require regular position reports. Insurance needs to cover the actual risks and name the correct beneficiaries. If the warehouse can exercise a general lien for unrelated debts, token holders may not have the clean collateral position they expect.
Daily token supply need not change for ordinary moisture adjustment, but the coverage ratio must. Haircuts should absorb expected shrinkage, price volatility and operational delay. A trigger can suspend new minting or require replenishment when coverage approaches a floor.
Physical redemption gives the token a direct commodity use, but it introduces nominations, transport, minimum quantities, documents and acceptance testing. Cash settlement is easier for fractional investors, but it converts the holder’s final claim into a payment obligation of the issuer or settlement agent.
If cash settlement uses a French benchmark while inventory sits in Central Europe, local transport and grade differentials may widen. The documents must state whether the holder receives the benchmark price, the actual sale proceeds or a formula adjusted for location and quality. The party bearing that basis risk should be visible.
Physical delivery has its own basis risk. A holder may receive eligible corn but pay more for transport than expected. Transparent redemption costs are more credible than claims of instant global liquidity.
A transferable token that evidences title to corn may be analysed differently from a debt security, a managed investment interest or a cash-settled derivative. Under MiCA, crypto-assets that qualify as financial instruments remain outside MiCA and within existing financial-services law. ESMA’s March 2025 classification guidelines reinforce the substance-over-form approach.
Issuers should document why the chosen classification fits the rights, transferability and economic purpose. A title token does not become unregulated merely because a commodity exists underneath it. Distribution, custody, trading, AML and consumer or investor-protection rules may still apply.
The term “securitisation” should also be used carefully. The EU Securitisation Regulation concerns tranched credit risk. Pooling corn inventory and issuing one class of tokens is not automatically a regulated securitisation, though the token may still be a security.
Smart contracts can enforce transfer restrictions and token burns. They cannot sample corn, confirm a warehouse lien or arrange a truck. The service-level agreement for those functions is part of the product.
A credible corn token names the quality, location, control party, settlement method and remedy. It makes clear whether the investor owns grain, holds a secured claim or finances a future delivery. It also explains how food and feed safety events affect the asset.
Lympid’s commodities tokenization infrastructure can support controlled issuance and investor workflows. The commodity contract, silo control and regulatory analysis remain essential. For related context, read the mechanics of asset tokenization and how security tokens differ from other token claims.
The best test is a failed delivery simulation. If the operator can identify the supporting corn, stop the corresponding release, apply the documented quality remedy and pay or deliver according to the contract, the token has an operational foundation. If not, it is only a transferable record of an unsettled promise.
Book a call with us today and get a free assessment.