September 5, 2025
August 27, 2026
Author: João Lages
Commodity tokenization is often discussed as a way to bring metals, energy products or agricultural goods on-chain. The practical question is more basic: what does the holder own, and how is the claimed inventory controlled while the token is outstanding?
A digital ledger can make transfers and reporting easier. It cannot establish clean title to goods, prevent double pledging, verify grade or guarantee that an inventory record matches what is actually in storage. The commercial and legal infrastructure around the commodity remains the investment product.
This article is general educational information, not legal, tax, financial or investment advice.
“One tonne of copper” or “one barrel of oil” is rarely specific enough. The relevant asset may vary by grade, quality, location, delivery point, storage condition and permitted substitution. Agricultural goods can degrade. Industrial materials may be commingled or processed. Energy products may exist only as an entitlement under a storage or delivery contract.
The token terms should therefore describe the underlying commodity, the valuation basis, the relevant inventory unit and whether holders have title, security, a pooled entitlement, a note or simply price exposure. A product linked to future agricultural production is not the same as one backed by current inspected inventory, even if both use the word commodity.
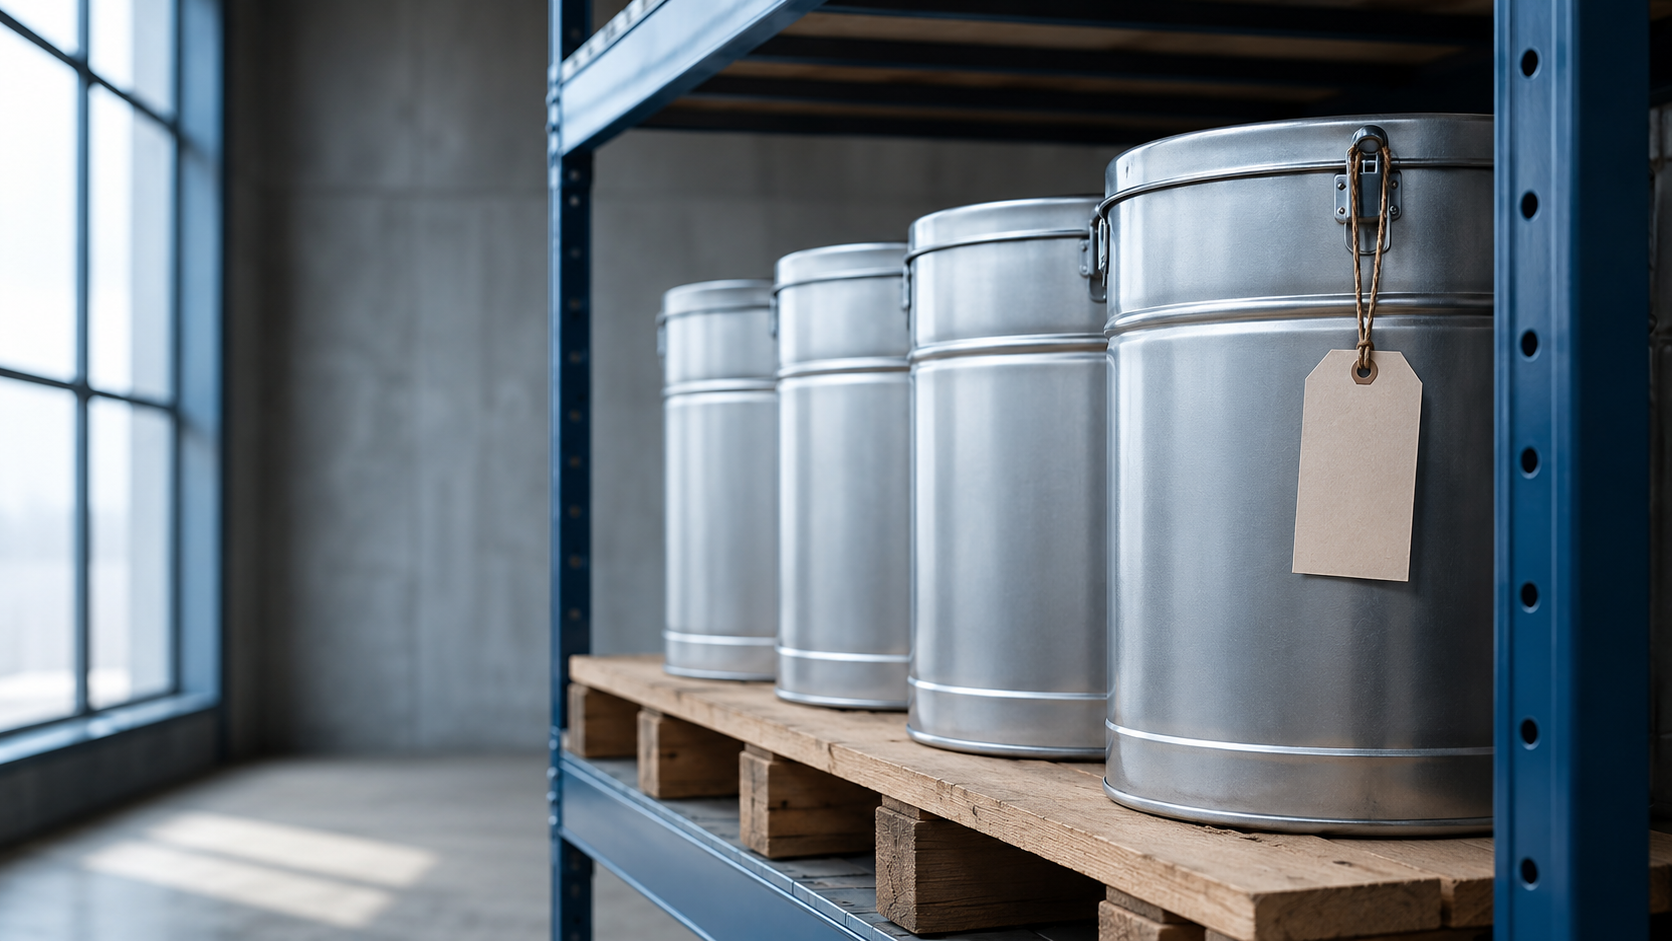
A warehouse receipt or inventory statement may be an important control, but it needs to be read alongside title documents, liens, insurance, release authority and the warehouse agreement. Storage of goods does not automatically prove that they are unencumbered or available for token holders.
A robust workflow has an independent inspection or custodian acceptance point before issuance. The issuer then reconciles the investor register, token supply and inventory report at defined intervals. It must also specify who can authorise substitution, processing, release, sale or correction. The key operational safeguard is not that data cannot be edited. It is that a correction requires evidence and leaves a transparent audit trail.
Physical delivery is often presented as a simple benefit. In practice, it involves minimum quantities, loading, transport, customs, taxes, insurance, timing, location and sometimes substantial handling costs. A small fractional holding may be economically impractical to deliver.
Terms should explain whether a holder can claim physical delivery, sell to the issuer or a dealer, or receive cash proceeds from a managed sale. They should also state how the price is calculated and which costs are deducted. These details determine whether a token represents practical commodity access or only an economic reference.
A benchmark price is not necessarily the net value of inventory in a specific warehouse. Grade, location, transport, storage, financing, spoilage and local demand create basis risk. If the instrument references a published benchmark while the underlying goods are valued differently, investors need a clear explanation of who bears the difference.
Liquidity is a separate issue. A blockchain transfer function does not create buyers, market makers or a permitted trading venue. Issuers should distinguish a technically transferable token from an active secondary market and avoid implying that fractionalisation guarantees an exit.
A commodity-related token can be a financial instrument, an in-scope crypto-asset, a contractual claim or another arrangement governed by national law. MiCA excludes financial instruments, and ESMA’s classification guidelines require a substance-over-form analysis. The fact that the reference asset is physical does not settle the regulatory outcome.
For issuers that have defined the instrument and distribution route, Lympid’s commodities-tokenization infrastructure can support onboarding, payments, investor administration and reporting. Those services should be built around the actual goods, claim and operational controls.
Commodity tokenisation can create more transparent administration around physical goods. It does not remove the need for warehouse control, title verification, inspection, insurance and a realistic delivery or sale process. The token becomes useful when it makes those controls easier to audit.
Book a call with us today and get a free assessment.