October 23, 2025
September 27, 2026
Author: João Lages
Tokenizing real estate income is not the same as putting a building on a blockchain. In most transactions, the property remains where it has always been: held by an individual, company, fund or special-purpose vehicle and recorded under local property law. The token represents a financial or contractual claim connected to cash generated by that structure.
That distinction matters because rental income is not automatically distributable cash. Rent can be unpaid. Operating expenses, taxes, insurance, maintenance, capital expenditure, lender covenants and reserves all sit between headline revenue and an investor distribution. A credible tokenized-income product must define that path precisely, then keep the legal documents, bank accounts, property-management records and token ledger reconciled throughout the investment.
“Income token” is a commercial description, not a single legal instrument. Several structures can produce an income-linked return, and they give investors materially different rights.
The token should never be described as direct ownership of rent unless the legal arrangement genuinely transfers that claim. Nor should it be presented as title to the property when the land register identifies somebody else. The enforceable contract and authoritative ownership record prevail over the interface shown to investors.
The most important commercial definition is the amount on which investor participation is calculated. “Rental income” can refer to at least five different numbers:
These figures can diverge sharply. A fully occupied property may show strong contracted rent while producing little distributable cash because tenants pay late, a roof must be replaced or refinancing costs increase. Documents should therefore identify the exact cash-flow definition, accounting period, permitted deductions, reserve policy and treatment of exceptional items. If the issuer or property manager can change these inputs, investors need a defined approval process and reporting trail.
A token contract can calculate allocations, but it cannot decide which claims rank first. The waterfall must come from the legal documents and should match the movement of cash through controlled accounts.
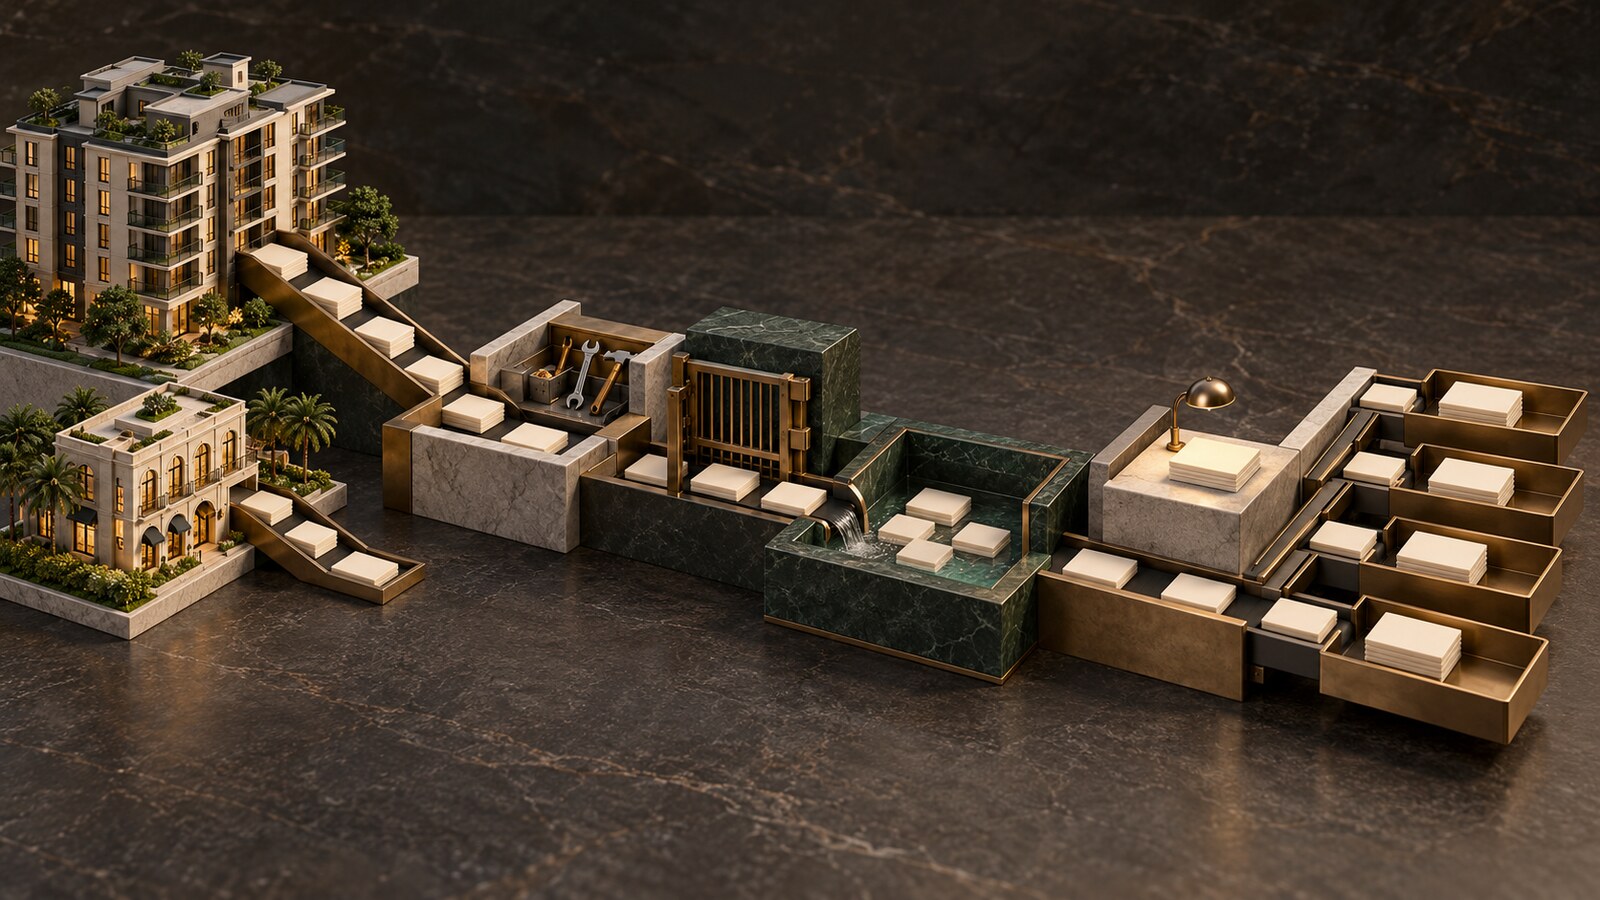
A typical single-property structure might apply collected revenue in this order:
Each step needs objective evidence. Bank data establishes cash received, invoices support property expenses, the loan servicer confirms debt payments and the corporate administrator confirms the investor register. Publishing a blockchain transaction without reconciling those records creates a transparent record of an unverified number.
Investors should also know what happens when cash is insufficient. Does an unpaid amount accrue as a debt, carry forward without interest, disappear for that period or trigger an event of default? A vague right to a “share of income” does not answer that question.
Consider a hypothetical apartment SPV with long-term tenants and senior bank financing. The sponsor wants to issue income-participating notes to fund part of the equity requirement.
The notes could reference quarterly distributable cash after collected rent, operating expenses, senior debt service and a documented repair reserve. The issuer would report occupancy, arrears, tenant concentration, operating expenses, reserve movements and loan covenant status. If a boiler replacement consumes the quarter's free cash, the token does not manufacture a distribution. The documents determine whether the missed participation carries forward.
Two decisions change the risk materially. First, a claim calculated on gross rent offers a larger-looking percentage but exposes the issuer to operating-cost volatility; a claim on cash after expenses gives investors a more realistic base but more discretion over deductible costs. Second, a subordinated note may receive payments before sponsor equity yet still rank behind the bank and secured creditors in insolvency. The product page should show that ranking clearly rather than presenting all “fractional property” exposures as equivalent.
A hotel illustrates why revenue and income should not be conflated. Room receipts fluctuate with occupancy, daily rates and seasonality. Food and beverage sales add revenue but also labour and inventory costs. Brand fees, management fees, utilities and furniture, fixtures and equipment reserves can absorb a substantial share of operating cash.
A hotel-linked instrument therefore needs a more granular formula than a residential-rent note. The issuer might define participation by reference to audited or independently reviewed cash after operating costs, management fees, debt service and the required refurbishment reserve. The reporting package should show occupancy, average room rate, revenue by segment, payroll, management charges and reserve movements. A sponsor should not use gross booking revenue as the headline “yield base” if the investor is paid from a much narrower residual amount.
The example also changes the reserve decision. Distributing every strong-season surplus can increase current yield while leaving the property unable to renovate rooms before the next cycle. Retaining cash protects the asset but delays investor payments. The governing terms should establish the reserve methodology and who may change it.
Real estate income originates off-chain. Tenants pay bank accounts, managers approve invoices, lenders control covenants and tax authorities collect in fiat. The digital ledger becomes reliable only when those events are imported and reconciled under a controlled process.
A workable operating model should identify:
Automation can reduce repetitive administration. It cannot remove segregation of duties. The same person should not be able to amend the cash-flow input, approve the distribution and alter the investor register without an independent control.
In the EU, describing an instrument as an RWA token does not decide its regulatory treatment. The rights attached to it may cause it to qualify as a transferable security or another financial instrument. ESMA's guidelines on the qualification of crypto-assets as financial instruments emphasise a substance-based assessment. A token that is a financial instrument is governed by the relevant securities framework rather than MiCA's ordinary regime for crypto-assets that are not financial instruments.
That classification affects issuance, distribution, investor protection and secondary transfers. Investment services involving financial instruments fall within the framework established by MiFID II. A public offer of securities also requires analysis under the Prospectus Regulation, consolidated on 5 June 2026, including the applicable exemption and national rules.
If capital from several investors is pooled under a defined investment policy for their benefit, the structure may require analysis as an alternative investment fund. Tokenization does not remove that question. Directive (EU) 2024/927, commonly called AIFMD II, amended the EU framework for alternative investment fund managers, including liquidity-risk management and other operating requirements. Issuers need jurisdiction-specific legal and tax advice before settling the instrument and distribution route.
Lympid's guide to a legal tokenization setup in Europe explains why classification should precede smart-contract configuration.
An income-linked token may be transferable without being liquid. A willing buyer still needs current lease data, expense history, valuation evidence, information about debt and confidence that distributions are calculated consistently. A compliant token standard can restrict transfers to eligible investors; it cannot create demand for an unfamiliar single-asset security.
The valuation method should reflect the instrument. Equity exposure depends on property value, debt and residual cash. A note depends on contractual payments, credit risk, security, duration and recovery. A revenue-participation right depends on the defined cash-flow base and the likelihood of payment. Displaying the latest property valuation as the token price can be misleading when the token is a subordinated debt claim or when material liabilities sit ahead of it.
Secondary-transfer claims should therefore identify the actual route: bilateral bulletin board, brokered transfer, regulated venue or issuer redemption. Investors should assume that they may need to hold until refinancing, property sale or contractual maturity unless a functioning exit mechanism is evidenced.
The sponsor should begin with the property economics and work outward. Map every source and use of cash, then select the legal instrument that expresses the intended priority and return. Confirm the regulatory route, document the waterfall, establish controlled accounts and decide which records are authoritative. Only after those decisions should the token, portal and reporting integrations be configured.
For sponsors assessing implementation partners, the comparison of real-estate tokenization provider models separates software, regulated distribution and lifecycle administration. Lympid's real-estate tokenization service is relevant where a sponsor needs a coordinated European structure, branded investor journey and distribution arrangements rather than token software in isolation. Asset diligence, valuation, local property law and tax advice remain separate responsibilities.
Development projects need a different architecture because income may be absent during construction. The guide to real-estate development capital stacks explains how drawdowns, senior debt, mezzanine capital and exit proceeds change the investor claim.
A real estate income token is credible when an investor can answer five questions without relying on marketing language: What legal claim do I own? Which cash-flow number determines my return? Which claims and reserves are paid before me? Who verifies the calculation and controls the accounts? What happens after a shortfall, default or sale?
If those answers exist only in the interface or smart contract, the structure is incomplete. When they are embedded consistently in the instrument terms, property operations, bank controls, investor register and token rules, tokenization can make income administration more programmable and auditable. The value lies in that alignment, not in treating rent as if it became liquid merely because it was represented digitally.
Book a call with us today and get a free assessment.